Private Client Tax and Trust Services
How can we help you with private client tax and trust services?
Every individual and family’s tax position is unique, yet the need is always the same: clear advice you can act on, delivered by people who understand your goals and protect your wealth with care.
At Rayner Essex, our private client specialists work with entrepreneurs, senior executives, international families, trustees, and landed estates. We understand that the needs of each of our clients are different.
We will help you remain fully compliant with HMRC while structuring your affairs in a way that preserves your wealth and supports your long-term plans.
We can support you with:

Personal tax advice
We provide tailored guidance on structuring your personal tax affairs efficiently, including moving to or from the UK, succession planning, and working alongside your financial and legal advisers.
Self-assessment and personal tax compliance
Our expertise extends to preparation and submission of self-assessment tax returns, capital gains tax returns, and other HMRC filings, ensuring all obligations and tax payments are met on time.
Property and landlord tax
Support with rental accounts, non-resident landlord rules, and advice on the complex legislation affecting residential property, including CGT submissions and mortgage interest restrictions.
HMRC enquiries and disclosures
Representation in HMRC enquiries and guidance on disclosure facilities, reducing penalties and resolving matters swiftly.
Divorce and family settlements
Discreet, practical advice on the tax implications of family change, including property transfers, capital gains, and succession planning, turning complexity into clarity and helping you make sense of viable solutions.

Why use private client tax services from Rayner Essex?

Expert tax advice, simplifying complex tax matters with clear, tax-efficient and compliant planning.
We’re partner and director led, with a dedicated support team available to all times.
We take the time to understand your affairs, providing holistic, joined-up advice across personal tax, trust and business matters.
We help you protect your wealth, minimise tax, and secure your legacy with expert private client tax and trust planning.
What type of businesses can benefit from our private client tax and trust services?
Rayner Essex work with a wide range of businesses of various sizes and sectors.
Sole traders
Partnerships
Limited companies
Start-up businesses
Small owner-managed businesses
Medium sized businesses, Corporates
Private clients and individuals
Multinationals
Frequently Asked Questions
If you are required to submit a self-assessment tax return to HMRC, registration must be completed by 5 October following the end of the relevant tax year. The tax return submission deadline is 31 January following the end of the relevant tax year.
HMRC’s software does not support submission of tax returns for non-UK resident or non-UK domiciled individuals. Residence and domicile is a complex area and is often investigated by HMRC.
A capital gains tax return is not always required when an individual sells a property. Whether or not a return is required will depend on several factors, including but not limited to the type of property sold, the capital gain or loss on disposal, the use of the property throughout the period of ownership and the residence status of the vendor. Please note that if a capital gains tax return is required, the deadline for submission is usually 30 days from the date of completion. With high penalties for late submission, timely submission is key.
Testimonial
“Mark Moore has been managing my tax planning for several years enabling a perfect understanding of my needs. I have come to consider him as a friend and a trusted tax advisor. Ultimately, it’s the Tax Partners that lead Rayner Essex to deliver an exceptional professional service with a deep personal understanding”
Vikram Merchant
Meet our private client tax experts
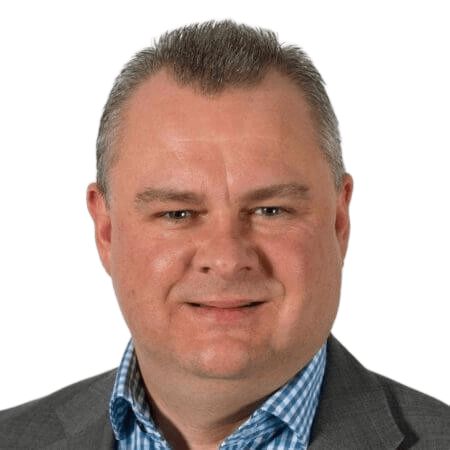
Mark Moore
Contact Mark MooreRelated News
 Read more about Autumn Budget 2026: key tax changes for businesses and individuals
On 28 October 2026, Chancellor of the Exchequer John Healey delivered his first Autumn Budget, announcing a series of tax
 Read more about The Tax Round: Autumn Edition 2026
In this autumn edition of the Tax Round, we bring together the latest tax news, legislative changes and regulatory developments affecting businesses and individuals across the UK.
 Read more about HMRC consultation on simplifying treaty relief from withholding tax on overseas interest
HMRC recently consulted on simplifying the process for obtaining treaty relief from UK withholding tax on interest paid to overseas